


MACRO ECONOMIC CALENDAR
Weekly Economic Calendar: Week of 14 September – 18 September 2026
Followme News Desk | September 14, 2026 | All times GMT+8
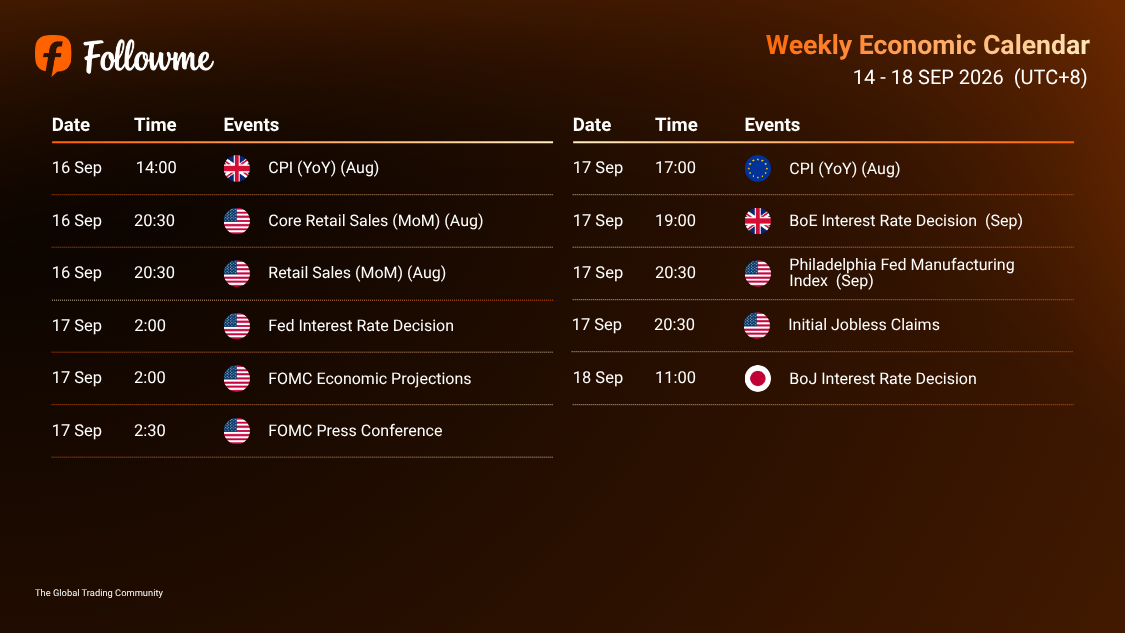
This week's economic calendar is heavily focused on UK CPI (YoY), U.S. Core Retail Sales and Retail Sales (MoM), the Fed Interest Rate Decision and FOMC Economic Projections, the FOMC Press Conference, EU CPI (YoY), the Bank of England Interest Rate Decision, the Philadelphia Fed Manufacturing Index, U.S. Initial Jobless Claims and the Bank of Japan Interest Rate Decision. Wednesday opens with UK CPI and U.S. Retail Sales before Thursday becomes one of the most loaded single sessions of the year. Fed decision, dot plot, press conference, EU CPI, BoE decision, Philly Fed and Claims all landing across the same morning and afternoon. Friday closes with the BoJ hold.
The Fed decision and FOMC Economic Projections are the standout events. After weeks of soft payrolls and decelerating inflation, this isn't just another hold. It's the meeting where the committee's rate path gets updated, and any downward revision to the median projection would validate the rate cut narrative that markets have been building toward since August. Powell's tone at 2:30 will set the direction for USD for the rest of the week and potentially well beyond it.
Key Events This Week
🕐 All times shown are GMT+8
| Date | Time | CCY | Event | Forecast | Previous |
|---|---|---|---|---|---|
| 16/9 | 14:00 | 🇬🇧 GBP | CPI (YoY) (Aug) | 2.90% | 2.60% |
| 20:30 | 🇺🇸 USD | Core Retail Sales (MoM) (Aug) | 0.20% | -0.20% | |
| 20:30 | 🇺🇸 USD | Retail Sales (MoM) (Aug) | 0.10% | 0.20% | |
| 17/9 | 02:00 | 🇺🇸 USD | ⭐ Fed Interest Rate Decision | 3.75% | 3.75% |
| 02:00 | 🇺🇸 USD | ⭐ FOMC Economic Projections | 0.30% | 0.80% | |
| 02:30 | 🇺🇸 USD | ⭐ FOMC Press Conference | 2.25% | 2.25% | |
| 17:00 | 🇪🇺 EUR | CPI (YoY) (Aug) | 3.30% | 2.90% | |
| 19:00 | 🇬🇧 GBP | BoE Interest Rate Decision (Sep) | 3.75% | 3.75% | |
| 20:30 | 🇺🇸 USD | Philadelphia Fed Manufacturing Index (Sep) | 24.10 | 41.4 | |
| 20:30 | 🇺🇸 USD | Initial Jobless Claims | 205K | 204K | |
| 18/9 | 11:00 | 🇯🇵 JPY | BoJ Interest Rate Decision | 1.00% | 1.00% |
Macro Analysis
🇬🇧 UK CPI (YoY)
UK CPI for August is forecast at 2.90% on an annual basis, a notable jump from 2.60% prior. That's a meaningful re-acceleration, if confirmed, it would give the Bank of England a genuine reason to stay cautious about cutting rates at Thursday's meeting. GBP tends to react strongly to inflation surprises in either direction, and a reading at or above 2.90% would likely support Sterling heading into Thursday's BoE decision. A miss that keeps the number closer to 2.60% would shift the calculus, traders would start pricing a more dovish BoE tone and GBP could give back ground quickly before the central bank even speaks.
🇺🇸 U.S. Core Retail Sales and Retail Sales
Core Retail Sales for August are forecast at 0.20%, recovering from -0.20% prior, while headline Retail Sales are forecast at 0.10%, a slight easing from 0.20% prior. The core number is the more significant of the two, a return to positive territory from -0.20% would suggest the consumer pulled back in July but hasn't abandoned spending altogether. A beat on core above 0.20% would be USD-positive and add to the resilience narrative heading into Thursday's Fed decision. A miss that stays flat or negative again would raise fresh questions about whether consumer demand is genuinely weakening, and could weigh on USD before the week's biggest session even arrives.
🇺🇸 Fed Interest Rate Decision, FOMC Economic Projections and FOMC Press Conference
This is the standout event of the week and one of the most consequential Fed meetings of the year. The Fed is expected to hold at 3.75%, unchanged from the prior decision. But this meeting comes with FOMC Economic Projections, the dot plot, which means markets will get a fresh read on where committee members see rates heading over the next 12 to 24 months. After weeks of softening labour market data and decelerating inflation, any downward revision to the median rate path would accelerate rate cut expectations dramatically and hit USD hard. The press conference at 2:30 is where Powell will either lean into the easing narrative or push back on it, and given how much positioning has shifted since the last meeting, the reaction could be sharp in either direction. This isn't just another hold; it's a hold that tells you where the next move is going.
🇪🇺 EU CPI (YoY)
Eurozone CPI for August is forecast at 3.30%, jumping from 2.90% prior. That's a significant acceleration in the annual rate, and it lands on the same day as the Fed decision, which makes Thursday an unusually complicated session for EUR/USD. If Eurozone inflation beats expectations at the same time the Fed sounds dovish, EUR/USD could rally sharply. If the Fed turns hawkish while EU CPI disappoints, the move goes the other way just as fast. A reading at or above 3.30% would reduce ECB easing expectations and provide EUR with a firm floor, particularly if it follows last week's German CPI beat.
🇬🇧 Bank of England Interest Rate Decision
The BoE is expected to hold at 3.75%, unchanged from the prior meeting. Coming the same day as Wednesday's UK CPI beat or miss, the statement tone will be heavily shaped by what the inflation data showed the day before. If UK CPI lands at 2.90% or above, the BoE can justify staying firm and GBP should hold its gains. If CPI disappointed on Wednesday, any BoE member voting for a cut would put meaningful pressure on Sterling. The dynamic between the BoE holding and the Fed's dot plot landing earlier in the morning makes Thursday a genuinely complex session for GBP/USD, both central banks are moving in the same session and the relative tone between the two will drive direction.
🇺🇸 Philadelphia Fed Manufacturing Index
The Philly Fed Manufacturing Index for September is forecast at 24.10, a sharp deceleration from 41.4 prior. Even with the drop, a reading above 20 still signals solid expansion, but a fall of this magnitude from the prior month will attract attention. Markets will want to know whether last month's strong 41.4 was a one-off or whether this pullback to 24.10 reflects a more durable slowing in mid-Atlantic factory conditions. A reading at or above 24.10 would reassure that manufacturing is still healthy. A reading that drops below 20 would raise more concern about the industrial outlook in a session already dominated by the Fed and BoE decisions.
🇺🇸 U.S. Initial Jobless Claims
Claims are forecast at 205K, ticking up from 204K prior, barely any change. In a session carrying the Fed decision, EU CPI, the BoE and the Philly Fed, claims won't be the story on Thursday unless they're a clear outlier. A reading below 200K would add a positive footnote to a session that may already be dovish in other ways. A jump toward 215K or above would be hard to ignore coming so soon after the recent soft NFP print, and would stack another bearish USD signal onto a session already full of them.
🇯🇵 Bank of Japan Interest Rate Decision
The BoJ is expected to hold at 1.00%, unchanged from the prior meeting. After hiking to 1.00% last month, a hold is the most likely outcome, the BoJ rarely moves in consecutive meetings unless the data compels it. What matters here is the language. Any signal that the BoJ is comfortable at 1.00% for now would be broadly neutral for JPY. A hint that another hike is being considered sooner than expected would push JPY stronger and put pressure on USD/JPY heading into the weekend. A dovish statement that walks back any near-term tightening expectations would allow USD/JPY to recover some ground if the Dollar has been under pressure all week from the Fed and CPI data.
Speculative Outlook for USD Traders
Thursday is the week. Everything else, UK CPI, Retail Sales, the EU CPI, is important context, but the Fed decision at 2:00, the dot plot and Powell's press conference at 2:30 are what this week is really about. The market has been pricing in earlier rate cuts for weeks now, driven by soft payrolls and decelerating inflation. What Thursday does is either validate that pricing or reset it. A dovish dot plot with Powell leaning toward cuts would confirm the market's view and send USD lower across the board. A hawkish hold, one that pushes back on the easing timeline, would be the bigger surprise and could trigger a sharp Dollar rally as short positions unwind.
The EU CPI and BoE decision landing later on the same Thursday morning add further complexity. If Eurozone inflation beats at 3.30% while the Fed sounds dovish, EUR/USD could see some of the biggest moves of the year in a single session. If UK CPI has already strengthened GBP on Wednesday and the BoE holds with a firm tone while the Fed pivots, the week becomes a story of the Dollar falling against everything. Friday's BoJ hold rounds things out. If the tone is neutral, JPY settles and the week's USD selloff has a chance to consolidate before the next session begins.
🟩 Bullish USD Scenario — Stronger Dollar Case
- Fed Dot Plot Shows No Rate Cuts This Year — If the median projection holds rates steady through year-end without a downward revision, the dovish pricing that's built up over recent weeks gets unwound fast and USD rallies.
- FOMC Press Conference Sounds Firm — Powell dismissing the soft labour market data as temporary and emphasising that inflation needs more time would catch a lot of short-USD positioning off guard.
- Core Retail Sales Beat 0.20% on Wednesday — Consumer spending recovering more than expected would set a constructive tone before the Fed even speaks and reinforce the resilience narrative.
- EU CPI Disappoints Below 3.30% — A softer Eurozone inflation print while the Fed sounds firm would hit EUR/USD from both sides simultaneously and deliver a sharp USD rally on Thursday.
- UK CPI Misses Below 2.90% — A softer-than-expected UK inflation reading on Wednesday would weaken GBP and set a risk-off tone before the Fed session begins.
- BoJ Signals Another Hike Is on the Table — A more hawkish BoJ statement would strengthen JPY and reduce the carry trade pressure on USD/JPY, which could provide an indirect floor for broader USD sentiment.
🌡 Wild Cards — High Whipsaw Risk
- Dovish Fed Then Hot EU CPI — If the Fed turns dovish at 2:30 and sends USD lower, but EU CPI then beats 3.30% later in the morning, EUR/USD could swing dramatically in a short window as two major forces pull in the same direction simultaneously.
- Dot Plot One Cut vs Two Cuts — The difference between the median showing one cut versus two cuts this cycle could move markets more than any other single data point this week. USD pairs could flip direction multiple times as traders debate what the number implies.
- BoE Vote Split on Thursday — If the BoE decision reveals an unexpected number of members voting for a cut, GBP could sell off sharply even if the headline rate holds, creating cross-market moves that complicate EUR/USD and USD/JPY positioning at the same time.
- Philly Fed Drops Below 20 — A reading that falls further than the already sharp deceleration from 41.4 to 24.10 would be hard to dismiss and could amplify any bearish USD reaction from the Fed session earlier in the morning.
- Retail Sales and Core Both Miss Wednesday — A soft consumer spending print before the Fed would add to the momentum toward dovish positioning and could make Thursday's session more one-sided than usual.
- BoJ Surprise Guidance on Friday — Any unexpected signal from the BoJ, hawkish or dovish, could produce sharp JPY moves on Friday that set a difficult tone for USD heading into the following week.
🔴 Bearish USD Scenario — Weaker Dollar Case
- Fed Dot Plot Shifts Lower — Even a single downward revision in the median rate projection would validate the market's dovish lean and send USD broadly lower as rate cut expectations lock in.
- Powell Signals a Cut Is Coming Soon — Any language from Powell that frames the September or November meeting as a live decision for a cut would hit USD hard and fast at 2:30 Thursday morning.
- Core Retail Sales Stay Flat or Miss — A reading at or below 0.00% on Wednesday would add consumer weakness to the soft labour market picture and set an even more bearish USD tone heading into Thursday.
- EU CPI Beats 3.30% Alongside a Dovish Fed — The combination of rising Eurozone inflation and a Fed that's moving toward cuts would be one of the more powerful EUR/USD bullish setups the market has seen in recent months.
- UK CPI Beats 2.90% and BoE Holds Firm — If Sterling gets a lift from strong inflation on Wednesday and the BoE reinforces that with a firm tone on Thursday, GBP/USD could push meaningfully higher while USD is already under pressure.
- Claims Jump Above 210K on Thursday — Another deterioration in claims in the same session as the Fed decision would compound the bearish USD narrative and make any attempted Dollar recovery very difficult to sustain.
Check out the full calendar here: Followme Economic Calendar Tool
Follow Followme for the newest market updates
Download Followme Application
Follow us on:


免責事項:本記事で述べられている見解は著者の見解のみであり、Followmeの公式見解を反映するものではありません。Followmeは、提供された情報の正確性、完全性、信頼性について一切責任を負いません。また、書面で明示的に記載されている場合を除き、本記事の内容に基づいて行われたいかなる行動についても責任を負いません。

