


MACRO ECONOMIC CALENDAR
Weekly Economic Calendar: Week of 5 October – 9 October 2026
Followme News Desk | October 5, 2026 | All times GMT+8
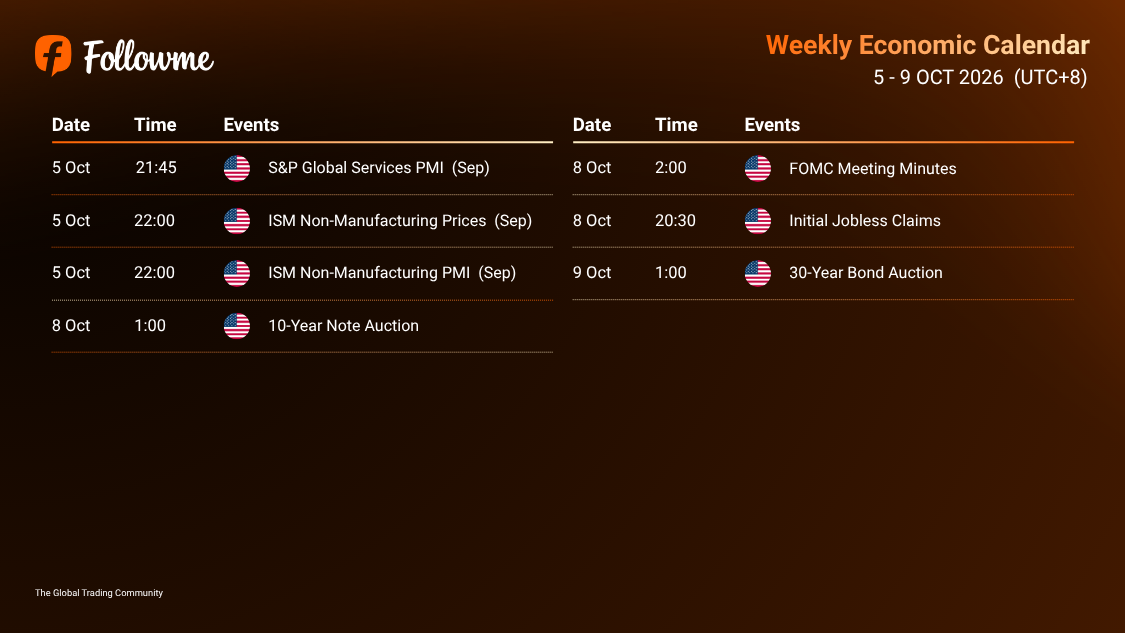
This week's economic calendar is focused on U.S. S&P Global Services PMI, ISM Non-Manufacturing PMI and Prices, the 10-Year Note Auction, FOMC Meeting Minutes, U.S. Initial Jobless Claims and the 30-Year Bond Auction. It's a quieter week by design. Monday opens with services data, Thursday carries the week's most concentrated session with the 10-Year Auction, FOMC Minutes and Claims all landing across the same morning and afternoon, and Friday closes with the 30-Year Bond Auction.
The FOMC Meeting Minutes are the standout event. After last week's soft NFP, the market is already leaning dovish what the minutes do is either validate that lean by showing the committee was already discussing cuts, or push back on it by reading as more patient than expected. In a week without a central bank decision or a major inflation print to anchor positioning, the minutes carry more weight than they normally would, and the reaction on Thursday could set USD's direction well into the following week.
Key Events This Week
🕐 All times shown are GMT+8
| Date | Time | CCY | Event | Forecast | Previous |
|---|---|---|---|---|---|
| 5/10 | 21:45 | 🇺🇸 USD | S&P Global Services PMI (Sep) | 55.8 | 56.5 |
| 22:00 | 🇺🇸 USD | ISM Non-Manufacturing Prices (Sep) | 70.0 | 70.3 | |
| 22:00 | 🇺🇸 USD | ISM Non-Manufacturing PMI (Sep) | 54.1 | 54.1 | |
| 8/10 | 01:00 | 🇺🇸 USD | 10-Year Note Auction | — | 4.68% |
| 02:00 | 🇺🇸 USD | ⭐ FOMC Meeting Minutes | — | — | |
| 20:30 | 🇺🇸 USD | Initial Jobless Claims | 201K | 198K | |
| 9/10 | 01:00 | 🇺🇸 USD | 30-Year Bond Auction | — | 5.22% |
Macro Analysis
🇺🇸 U.S. S&P Global Services PMI
S&P Global Services PMI for September is forecast at 55.8, easing from 56.5 prior, a pullback but still firmly in expansion. The services sector has been the most resilient part of the U.S. economy this year, so any deceleration from the recent highs gets attention. A reading that holds closer to 56.5 or above would push back on the narrative that services momentum is fading and give USD a constructive start to a week that's otherwise light on top-tier data. A sharper drop below 55 would raise genuine questions about whether the services sector is finally starting to slow in a way that the manufacturing data has been hinting at for some time.
🇺🇸 U.S. ISM Non-Manufacturing PMI and Prices
ISM Non-Manufacturing PMI for September is forecast at 54.1, unchanged from 54.1 prior, no change at all. ISM Non-Manufacturing Prices are forecast at 70.0, easing fractionally from 70.3. A PMI reading that holds at 54.1 confirms the services sector is still expanding at a healthy pace, but doesn't add much new information. The price component is the more interesting read, if it stays close to 70.0 while the PMI holds firm, it signals that services inflation isn't cooling meaningfully despite the broader disinflationary trend. That's the kind of split that keeps the Fed cautious and prevents USD from selling off too aggressively.
🇺🇸 U.S. 10-Year Note Auction and Bond Market Sentiment
The 10-Year Note Auction comes with a previous yield of 4.68%. After last Friday's NFP result and whatever shift in rate expectations followed, this auction will reflect how bond markets are positioning on the Fed's path. Strong demand, particularly a yield clearing below 4.68%, would signal that investors are pricing in earlier and more aggressive Fed cuts, reinforcing any USD weakness that carried over from the prior week. A weak auction clearing above 4.68% would suggest bond buyers aren't convinced the easing cycle is as aggressive as equities or currency markets might be pricing, and could provide USD with a quiet lift before the FOMC Minutes arrive an hour later.
🇺🇸 FOMC Meeting Minutes and Fed Policy Signals
The FOMC Meeting Minutes from the most recent Fed decision land Thursday at 2:00, and in a week that otherwise carries relatively little top-tier data, this release carries outsized weight. Markets will be looking for any language that gives more colour on how close the committee is to cutting, whether there's meaningful disagreement among members, and how they're weighing the recent softness in labour market data against still-sticky services inflation. A set of minutes that reads as more dovish than the statement itself suggested would accelerate rate cut pricing and hit USD. A hawkish lean, particularly any language suggesting members are not in a rush, could provide USD with a meaningful reprieve in a week where the Dollar has had little else to push back against.
🇺🇸 U.S. Initial Jobless Claims
Claims are forecast at 201K, ticking up from 198K prior, a small move but worth watching after last week's soft NFP. If the payroll data was weak but claims remain contained, it creates a slightly confusing picture, job creation slowing but layoffs not accelerating. A reading at or below 201K would suggest the labour market is softening at the top end but hasn't broken, which gives the Fed a little more time before feeling compelled to cut aggressively. A jump above 210K would be much harder to explain away and would compound the bearish USD narrative that's been building since last week's employment data.
🇺🇸 U.S. 30-Year Bond Auction
The 30-Year Bond Auction, with a previous yield of 5.22%, gives markets a read on appetite for very long-dated U.S. debt. Coming the morning after the FOMC Minutes, the auction will trade in whatever environment the minutes created. A strong auction, yields clearing below 5.22%, would confirm that investors are extending duration in anticipation of lower rates, reinforcing the dovish Fed narrative. A weak auction with elevated yields would push back on that view and suggest that even if the Fed is moving toward cuts, the long end isn't convinced the inflation fight is over. For USD, a weak long-end auction is the more USD-supportive outcome. It keeps yields elevated and reduces the pressure on the Dollar heading into the following week.
Speculative Outlook for USD Traders
This is a genuinely quieter week than what preceded it, but that makes each release hit harder in isolation. Monday's services data carries the early tone, if S&P Global and ISM both hold firm near their forecasts, the services narrative stays intact and USD has a reasonable footing heading into Thursday. The week then waits for Thursday's cluster: the 10-Year Auction at 1:00, the FOMC Minutes at 2:00, and Claims at 20:30. All three land in the same session and will collectively set the Dollar's direction for the back half of the week.
The FOMC Minutes are the standout event. After last week's NFP and whatever it delivered, the market will be reading every word of the minutes for clues about timing. If the committee was already discussing cuts before the soft payroll data arrived, the case for near-term easing becomes much harder to resist and USD would feel the weight of that on Thursday. If the minutes read as patient and data-dependent without clear signals, the market might trim some of the dovish positioning and give USD a brief recovery before the 30-Year Auction on Friday provides one final read on long-end appetite.
🟩 Bullish USD Scenario — Stronger Dollar Case
- FOMC Minutes Sound More Patient Than Expected — If the committee language emphasises caution and data dependence without discussing cut timing, the market trims dovish positioning and USD recovers ground on Thursday.
- Services PMI Holds Near 56.5 on Monday — A reading that defies the expected pullback would signal that the economy's most important sector is still running hot and pushing back on the rate cut urgency narrative.
- ISM Non-Manufacturing Prices Stay Near 70 — Sticky services inflation keeps the Fed from feeling comfortable cutting aggressively and gives USD a floor even as growth data softens.
- 10-Year Auction Clears Above 4.68% — A weak bond auction Thursday morning would suggest markets aren't pricing in aggressive Fed easing and keeps yields elevated, supporting USD.
- Claims Stay Below 201K — Contained jobless claims would suggest the labour market softening is gradual rather than accelerating and removes one of the main arguments for urgent Fed action.
- 30-Year Auction Disappoints on Friday — A weak long-end auction would push back on the idea that the inflation fight is over and keep the long-end yield elevated, providing a modest but real USD floor heading into the following week.
🌡 Wild Cards — High Whipsaw Risk
- FOMC Minutes Reveal Deep Disagreement — If the minutes show significant internal debate about the timing of cuts, the market may struggle to form a clean read and USD could swing in both directions as different lines get parsed and repriced.
- Services PMI Miss While ISM PMI Holds — A split between the two services readings on Monday would create conflicting signals about the sector's health and generate choppy USD price action as the market tries to decide which number to trust.
- 10-Year Auction Weak Then FOMC Minutes Dovish — A weak bond auction at 1:00 that pushes yields higher, followed immediately by dovish FOMC minutes at 2:00 that pull yields lower, would create violent intraday swings in both bonds and USD within the same morning session.
- Claims Jump Above 210K After Soft NFP — A second consecutive deterioration in labour market data within a week of each other would be difficult to dismiss and could trigger a sharp USD selloff in a session where the FOMC Minutes may have already started the move.
- 30-Year Auction Strong Amid Soft Data — A strong long-end auction with yields clearing well below 5.22% would signal that bond markets are fully committing to the rate cut story, which is typically USD-bearish and could extend any Dollar weakness into the following Monday.
- Services Data Both Disappoint Monday — If both S&P Global and ISM Non-Manufacturing PMI miss on the same day, the services sector which has been the last pillar of U.S. economic resilience starts to look shaky, and USD struggles to find support heading into Thursday.
🔴 Bearish USD Scenario — Weaker Dollar Case
- FOMC Minutes Show Clear Cut Discussion — Any explicit debate about cut timing from within the committee would accelerate rate cut pricing and hit USD hard at 2:00 Thursday morning, compounding last week's NFP-driven weakness.
- Claims Jump Above 210K on Thursday — A clear rise in claims following last week's soft payroll print would confirm that the labour market is deteriorating on multiple fronts and remove one of the remaining arguments for USD support.
- Services PMI Drops Below 55 on Monday — A sharper-than-expected fall in either services reading would suggest that even the economy's strongest sector is finally feeling the weight of the current rate environment.
- ISM Non-Manufacturing Prices Fall Below 68 — A meaningful drop in services inflation would reduce the last piece of the inflation-is-sticky argument and make it very difficult for the Fed to justify holding at current rates for much longer.
- 30-Year Auction Clears Well Below 5.22% — Strong long-end demand would signal that bond markets are fully positioned for earlier and deeper cuts, reinforcing the bearish USD narrative heading into the following week.
- 10-Year Auction Demand Signals Earlier Cuts — A strong 10-Year clearing well below 4.68% would suggest bond investors are moving aggressively toward a lower rate environment, adding front-end pressure to USD that compounds the FOMC Minutes reaction an hour later.
Check out the full calendar here: Followme Economic Calendar Tool
Follow Followme for the newest market updates


免責事項:本記事で述べられている見解は著者の見解のみであり、Followmeの公式見解を反映するものではありません。Followmeは、提供された情報の正確性、完全性、信頼性について一切責任を負いません。また、書面で明示的に記載されている場合を除き、本記事の内容に基づいて行われたいかなる行動についても責任を負いません。

