


MARKET REVIEW FOREX FED
Fed Minutes Back Another Hike as Yields Hit 2002 Highs
September FOMC minutes point to one more rate hike before year-end, the 10-year Treasury yield reaches its highest level since 2002, and the dollar index presses back against its 18-month high while gold slips to a two-month low.
Followme News Desk | October 8, 2026
The Fed didn't need to say anything new on Wednesday. The minutes of its September 15-16 meeting did the talking, and the message was blunt: inflation hasn't come down enough, and most officials think one more rate hike is likely before the year is out.
The vote to lift the federal funds rate to 3.75%-4.00% was unanimous, 12-0. What's more revealing is the reasoning behind it. Many participants framed the hike as insurance against inflation staying stuck above target. A number of others went further, saying higher rates were needed based on their central forecasts alone, not just as a precaution. A couple of officials admitted they had raised their estimate of the neutral rate, which means today's policy is less tight than it looks on paper. Several said outright that current rates are not restrictive or only mildly restrictive.
The inflation picture explains the urgency. Fed staff estimated headline PCE inflation at 3.8% in August, with core PCE at 3.4%. Officials blamed elevated energy prices tied to the Middle East conflict, the AI investment boom pushing up demand and input costs, and the lingering effects of tariffs. Participants broadly judged the risks to inflation as tilted to the upside, and some worried that after more than five years above the 2% target, price expectations could start to slip their anchor.
That worry got some support on the same day. The New York Fed's Survey of Consumer Expectations showed households now expect inflation of 3.9% over the next year, up 0.3 percentage points and the highest reading since May 2023. Three-year expectations rose to 3.3%, though five-year expectations held at 3.0%.
Bond markets were already moving before the minutes landed. The 10-year Treasury yield hit 5.35% intraday, a level last seen in April 2002, and the 30-year reached 5.724%. The 10-year has now climbed more than 60 basis points since late July, when fighting in the Middle East resumed. Investors also sold Treasuries ahead of the $39 billion 10-year note auction, with a 30-year bond sale and a Treasury buyback both lined up for Thursday.
The dollar followed yields higher. USDX rose to 102.50 twice during the session, matching the level where Monday's rally stalled at its highest since April 2025, before easing to around 102.24-102.35. The euro, which makes up about 58% of the index, accounts for roughly three-quarters of the move, weighed down by another selloff in French government bonds. With German 10-year yields near 3.5%, the US 10-year now pays more than 1.8 percentage points over Bunds.
In commodities, Brent crude pushed back above $100 a barrel after Iran stepped up attacks on tankers in the Strait of Hormuz, although WTI eased 1.66% to around $88.45 later in the session. Gold took the brunt of the higher-yield environment, sliding as far as $4,066, a two-month low, before buyers stepped in near $4,100.
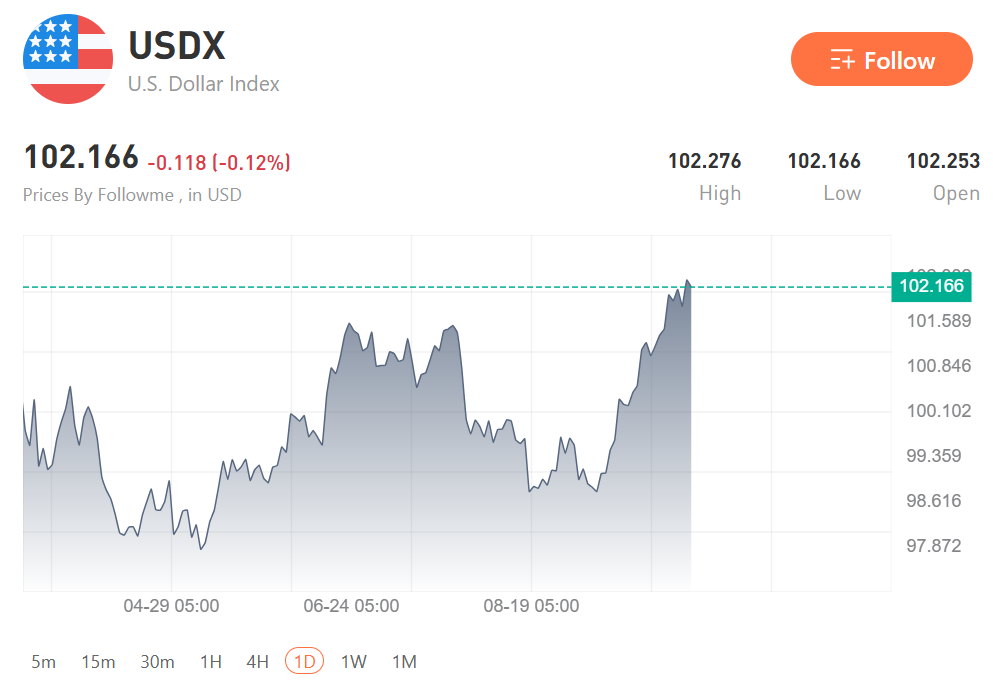
USDX price as of 8 October 2026 - View Live Chart →
The Facts
- Fed decision recap: Rates raised 25bp to 3.75%-4.00% on September 16 by a 12-0 vote. Interest on reserve balances lifted to 3.90%. Next FOMC meeting: October 27-28.
- Forward guidance: Most participants see another hike as likely appropriate by year-end. Several view policy as not restrictive or only mildly restrictive; A couple raised their neutral-rate estimates.
- Inflation: Staff estimate August PCE at 3.8% y/y and core PCE at 3.4%. Staff don't see inflation returning to 2% until 2029, and see risks skewed to the upside.
- Labor market: Unemployment at 4.1% in July and August; officials see the labor market close to maximum employment.
- Rate pricing: Around 18%-19% odds of an October hike and roughly 80% odds of a hold; about 85% odds of a hike by December (Prime Terminal).
- Treasuries: 10-year touched 5.35%, highest since April 2002; 30-year hit 5.724%. The 10-year has been up more than 60bp since late July.
- Consumer inflation expectations: One-year at 3.9% (highest since May 2023), three-year at 3.3%, five-year steady at 3.0%.
- US Dollar Index: Tested 102.50 twice, near its 18-month high and year-to-date peak of 102.53; last around 102.24-102.35.
- EUR weakness: French bond selling pressured the euro; The US-German 10-year spread is now above 1.8 percentage points.
- Oil: Brent back above $100 on Iranian attacks on Hormuz tankers; WTI eased to about $88.45.
- Gold: Two-month low at $4,066, recovered to around $4,115 (down 1.16% on the day). China's central bank extended its gold buying streak to 23 months.
What It Means
The minutes don't change the October picture much. Markets had already priced out a hike this month, and nothing on the record argues hard against that. What they do is harden December. When officials describe a hike as insurance, admit their neutral-rate estimates have moved up, and say policy isn't really restrictive, that's a committee leaning toward doing more, not less.
For the dollar, the important detail is where the yield pressure is coming from. Rising yields have been lifting USDX this year mostly when they reflect Fed rate expectations. The latest leg of the 10-year climb has had a lot to do with oil, heavy Treasury supply and term premium. That's a weaker foundation for dollar strength, and it helps explain why the index keeps stalling at 102.50 even with yields at multi-decade highs.
The euro is the swing factor. Because it carries so much weight in USDX, any calming in French bond markets could take the air out of the index quickly, even if US fundamentals don't change. On the other hand, a yield gap of more than 1.8 percentage points over German Bunds keeps a steady bid under the dollar for anyone chasing carry.
Gold is caught in a squeeze. Higher real yields and a firm dollar both work against a non-yielding asset, and the chart has been printing lower highs and lower lows. Steady central bank buying, led by China, and any escalation around Iran are the two things that can still put a floor under it.
Oil remains the variable linking everything. The Fed explicitly flagged that the longer energy prices stay high, the greater the risk of broader price pressures. Brent above $100 isn't just a commodity story; it feeds straight into inflation expectations, Treasury yields and, through them, Fed pricing.
What Traders Should Watch
USDX at 102.50: Rejected twice now. A daily close above the 102.53 year-to-date high opens a fresh leg higher. Failure keeps 101.75 in view, with the rising 50-day EMA near 100.50 as deeper support.
US 10-year yield: 5.35% is the line. A push through it, especially on weak demand at Thursday's 30-year auction, would keep pressure on gold and support the dollar.
XAU/USD: $4,100 is being held for now. Below it, the July 29 low at $3,996 and the year-to-date low at $3,941 come into play. Bulls need a move back above $4,200, then the 100-day and 50-day SMAs at $4,267 and $4,331.
Oil and Hormuz headlines: Brent above $100 keeps the inflation story alive. Reports that the Pentagon has ordered readiness for possible strikes on Iran mean headline risk is high in both directions.
EUR/USD and French bonds: The euro has been the main driver of USDX. A pause in the French debt selloff could trigger a sharp short-covering bounce.
USD/JPY near 158.00: The pair slipped below 158.00 on fears of renewed yen intervention. Remember the joint US-Japan intervention in late July.
Data and Fed speakers: Thursday brings initial jobless claims; Friday brings the University of Michigan consumer sentiment report. Any Fed speaker pushing back on, or leaning into, a December hike will move rate pricing.
The Bottom Line The Fed has made its bias clear, and the bond market is listening. The question for the next few weeks is whether the dollar can finally break 102.50 on rate expectations alone, or whether oil and Europe's bond troubles end up setting its direction instead. Until that level gives way, it remains the line every FX trader is watching.
Follow us for daily market insights, analysis, and the tools you need to trade with confidence.
Want to stay ahead of major macro developments that move the market? 👉 Follow Followme and check out the Weekly Economic Calendar
October 8, 2026 | This report is for informational purposes only and does not constitute financial advice. © 2026 Followme News
Download Followme Application
Follow us on:


免責事項:本記事で述べられている見解は著者の見解のみであり、Followmeの公式見解を反映するものではありません。Followmeは、提供された情報の正確性、完全性、信頼性について一切責任を負いません。また、書面で明示的に記載されている場合を除き、本記事の内容に基づいて行われたいかなる行動についても責任を負いません。

